
Form 3520 and 3520-A due-date calculator
Enter the filer's tax year end and the foreign trust's tax year end to see the due dates that the IRS instructions state for Form 3520 and Form 3520-A. Dates are adjusted for weekends only; legal holidays are not applied. The Form 3520 extended date applies only if an extension of time to file the income tax return has been granted. Under the instructions, a due date that falls on a Saturday, Sunday or legal holiday moves to the next day that is none of those.
How it works
The IRS instructions set Form 3520 for the 15th day of the 4th month after the end of the filer's tax year. They set Form 3520-A for the 15th day of the 3rd month after the end of the foreign trust's tax year. The tool adds those months to the year end you enter.
The instructions give an individual who meets a stated outside-the-United-States condition the 15th day of the 6th month, and an individual with a granted income tax return extension no later than the 15th day of the 10th month. A U.S. owner who attaches a substitute Form 3520-A files it by the Form 3520 due date.
Form 3520 and Form 3520-A can have different tax years and therefore different due dates. The tool takes a separate year end for each and shows each separately.
Worked example
For a calendar-year filer and a calendar-year trust, the ordinary Form 3520-A date is March 15 of the following year, and when that day falls on a weekend or legal holiday the due date moves to the next business day. With a timely Form 7004, the extended date is September 15, which also moves to the next business day when needed. The ordinary Form 3520 date is April 15 of the following year, and the granted-extension date is October 15 of the following year. March 15, April 15 and October 15 are nominal calendar-year dates; the tool moves each to the next weekday when needed and does not apply legal holidays.
What this tool does not do
The tool computes dates from the rules the instructions state. It does not determine which form or return applies, who the filer is, whether a condition is met or whether an exception applies. It does not apply legal holidays, and it does not give a filing determination.
Use the tool
Form 3520 uses the filer's own tax year. Form 3520-A uses the foreign trust's tax year. The two year ends can differ, so each has its own field. Every date shown is adjusted for weekends only; legal holidays are not applied.
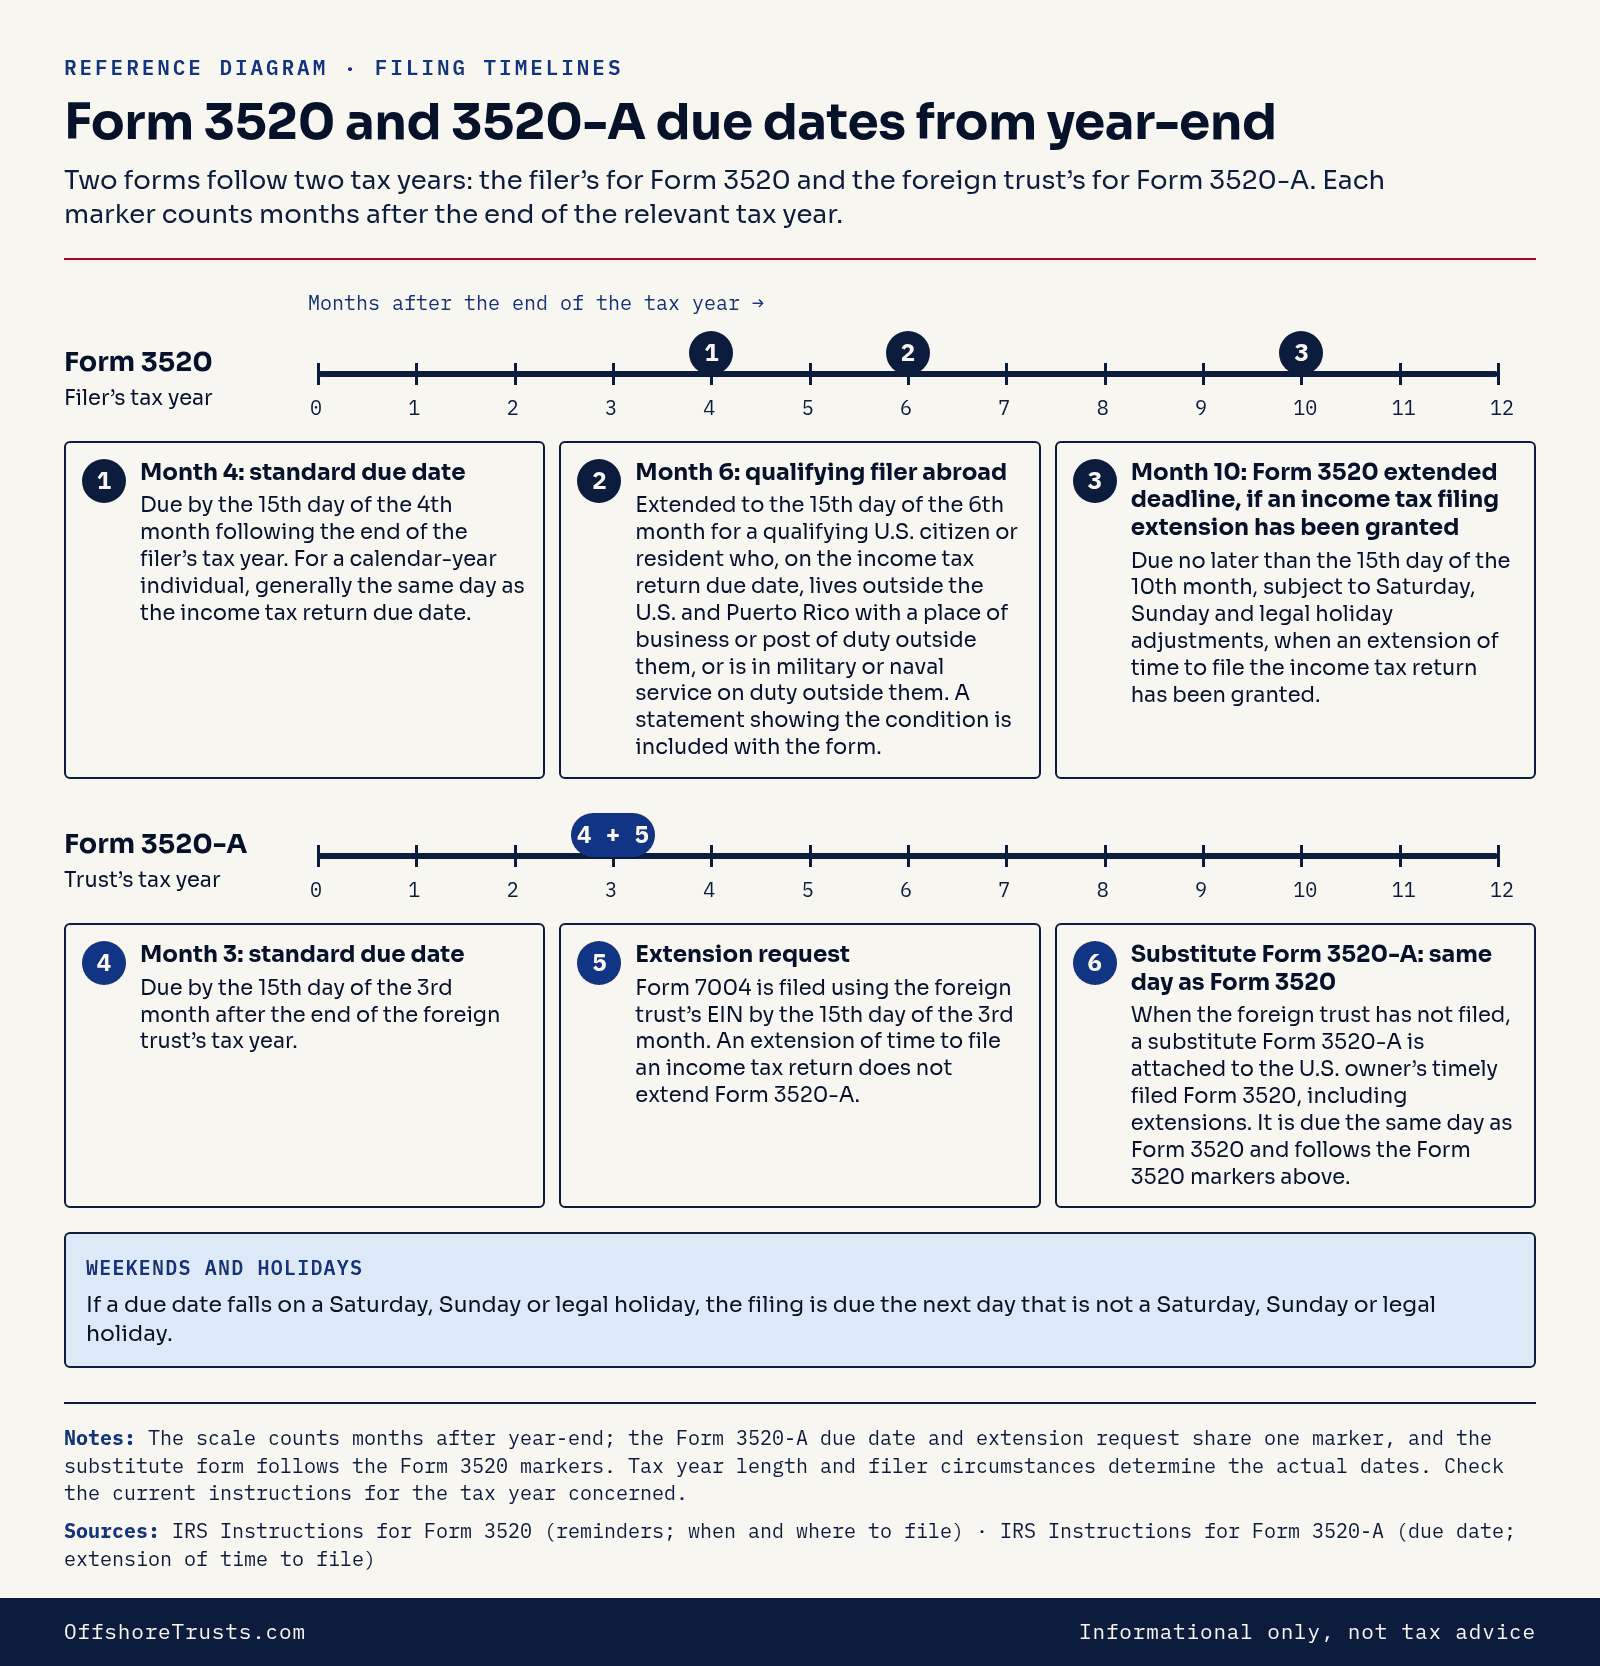
Data table for this infographic
| Form | Tax year used | Due date or condition | Description |
|---|---|---|---|
| Form 3520 | The filer's own tax year | Month 4: standard due date | Due by the 15th day of the 4th month following the end of the filer's tax year. For a calendar-year individual, generally the same day as the income tax return due date. |
| Form 3520 | The filer's own tax year | Month 6: qualifying filer abroad | Extended to the 15th day of the 6th month for a qualifying U.S. citizen or resident who, on the income tax return due date, lives outside the U.S. and Puerto Rico with a place of business or post of duty outside them, or is in military or naval service on duty outside them. A statement showing the condition is included with the form. |
| Form 3520 | The filer's own tax year | Month 10: Form 3520 extended deadline, if an income tax filing extension has been granted | Due no later than the 15th day of the 10th month, subject to Saturday, Sunday and legal holiday adjustments, when an extension of time to file the income tax return has been granted. |
| Form 3520-A | The foreign trust's tax year | Month 3: standard due date | Due by the 15th day of the 3rd month after the end of the foreign trust's tax year. |
| Form 3520-A | The foreign trust's tax year | Extension request | Form 7004 is filed using the foreign trust's EIN by the 15th day of the 3rd month. An extension of time to file an income tax return does not extend Form 3520-A. |
| Substitute Form 3520-A | Follows the filer's Form 3520 timeline | Same day as Form 3520 | When the foreign trust has not filed, a substitute Form 3520-A is attached to the U.S. owner's timely filed Form 3520, including extensions. It is due the same day as Form 3520 and follows the Form 3520 markers above. |
| All forms | The tax year used for each form | Weekends and holidays | If a due date falls on a Saturday, Sunday or legal holiday, the filing is due the next day that is not a Saturday, Sunday or legal holiday. |
| Notes | The filer's or the foreign trust's tax year, depending on the form | Scope | The scale counts months after year-end; the Form 3520-A due date and extension request share one marker, and the substitute form follows the Form 3520 markers. Tax year length and filer circumstances determine the actual dates. The instructions for the tax year concerned govern. |
| Sources | Forms 3520 and 3520-A | Documents | IRS Instructions for Form 3520 (reminders; when and where to file) · IRS Instructions for Form 3520-A (due date; extension of time to file) |
Questions and answers
Does an extension of my income tax return extend Form 3520-A?
No. The Form 3520-A instructions say an extension of time to file an income tax return does not extend Form 3520-A, and they point to Form 7004 filed with the foreign trust's EIN.
Why are there several Form 3520 dates?
The instructions state an ordinary date and separate dates for certain individuals living abroad and for filers with a granted return extension. The tool shows the ones you select.
Related resources
Related glossary terms
- U.S. beneficiary of a foreign trust: The Form 3520 instructions explain who is a U.S. beneficiary of a foreign trust and how that status relates to distributions and ownership, plus reporting.
- Foreign grantor trust: A foreign grantor trust is a foreign trust treated as owned by a grantor, often a U.S. person. Ownership brings Form 3520 and Form 3520-A reporting duties.
Related articles and guides
- Foreign gifts and trust distributions: Form 3520 reports foreign trust distributions and certain gifts from foreign persons. Reporting does not by itself determine whether a receipt is taxable.
Tools and official documents
- IRS form finder: Search form reference pages by keyword or number. Search by form title, number or description.
Related pages
Sources and data notes
- Internal Revenue Service, Instructions for Form 3520. https://www.irs.gov/instructions/i3520. Retrieved . Due dates, 6-month and 10-month rules, weekend and legal holiday rule, substitute Form 3520-A.
- Internal Revenue Service, Instructions for Form 3520-A. https://www.irs.gov/instructions/i3520a. Retrieved . Due date, Form 7004 extension and the statement that a return extension does not extend Form 3520-A.
Dates in this block record when each source was read for this page.