
IRS reporting for U.S. persons with foreign trusts
Forms, instructions and regulations that the IRS and FinCEN publish for U.S. persons connected to foreign trusts, foreign accounts and foreign entities, organized as a reference library.
How this section works
The guidance library summarizes statutes, regulations and publications in plain language.
The summaries do not decide which forms apply to a person, and they are not IRS publications.
Explore this section
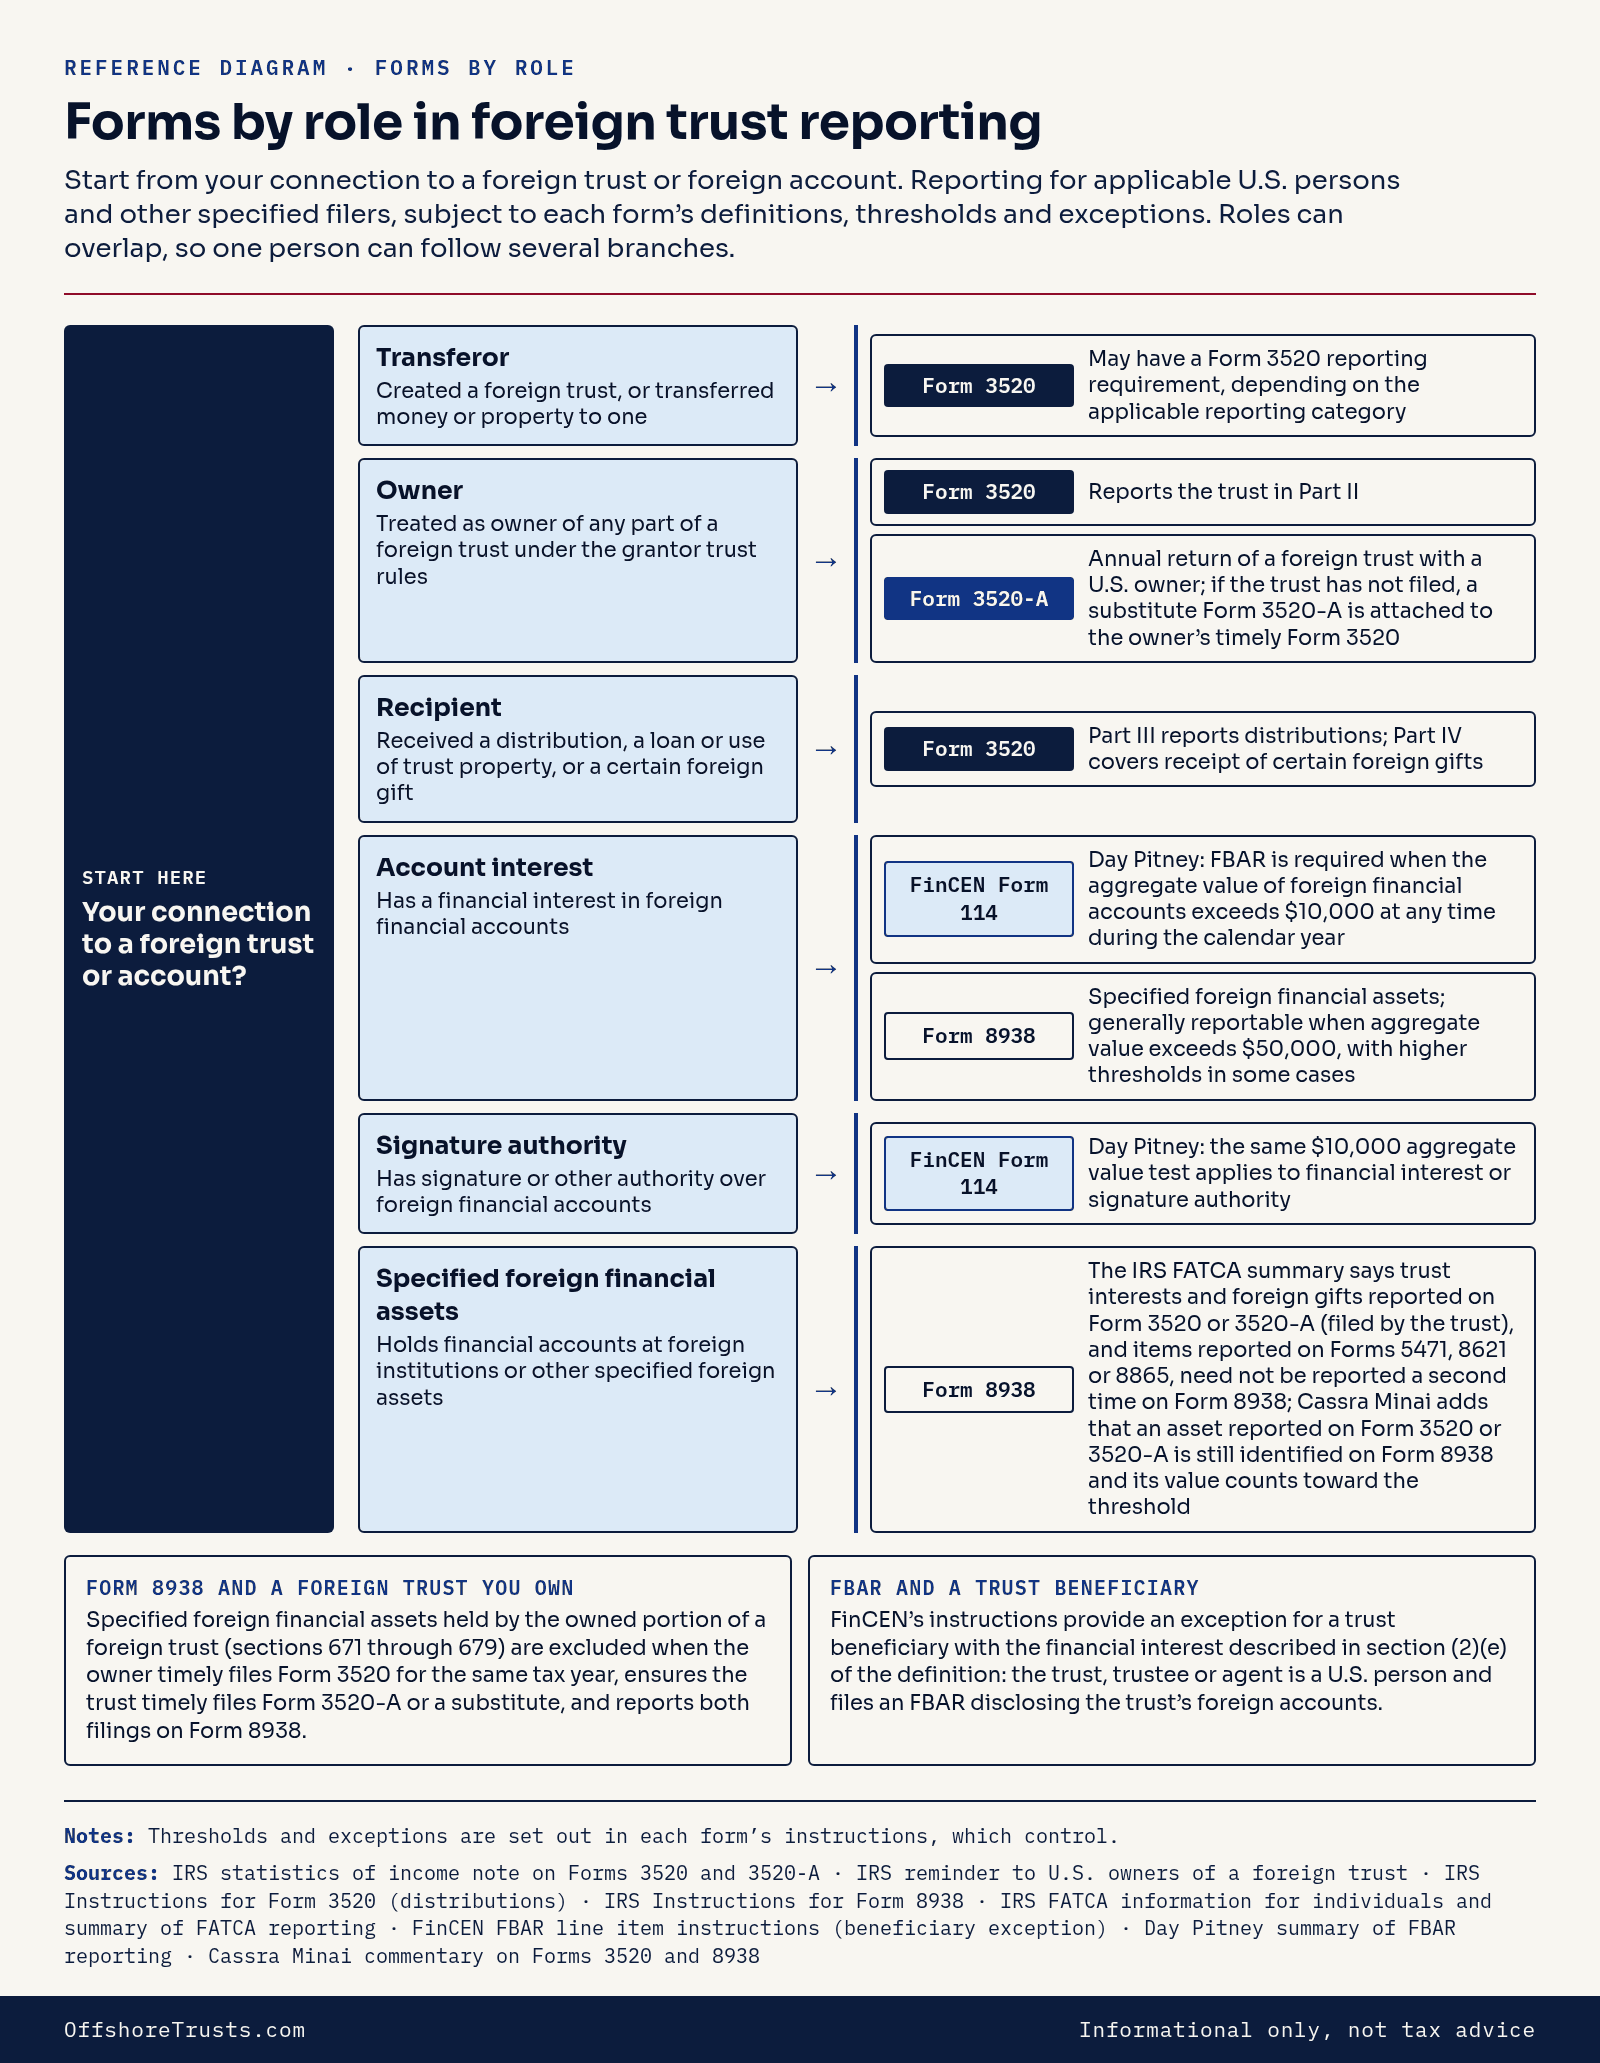
Data table for this infographic
| Role or topic | Connection or condition | Form or reporting | Details |
|---|---|---|---|
| Start here | Your connection to a foreign trust or account? | Roles can overlap, so one person can follow several branches. | |
| Transferor | Created a foreign trust, or transferred money or property to one | Form 3520 | May have a Form 3520 reporting requirement, depending on the applicable reporting category |
| Owner | Treated as owner of any part of a foreign trust under the grantor trust rules | Form 3520 | Reports the trust in Part II |
| Owner | Treated as owner of any part of a foreign trust under the grantor trust rules | Form 3520-A | Annual return of a foreign trust with a U.S. owner; if the trust has not filed, a substitute Form 3520-A is attached to the owner's timely Form 3520 |
| Recipient | Received a distribution, a loan or use of trust property, or a certain foreign gift | Form 3520 | Part III reports distributions; Part IV covers receipt of certain foreign gifts |
| Account interest | Has a financial interest in foreign financial accounts | FinCEN Form 114 | FBAR is required when the aggregate value of foreign financial accounts exceeds $10,000 at any time during the calendar year |
| Account interest | Has a financial interest in foreign financial accounts | Form 8938 | Specified foreign financial assets; generally reportable when aggregate value exceeds $50,000, with higher thresholds in some cases |
| Signature authority | Has signature or other authority over foreign financial accounts | FinCEN Form 114 | The same $10,000 aggregate value test applies whether the person has a financial interest or signature authority |
| Specified foreign financial assets | Holds financial accounts at foreign institutions or other specified foreign assets | Form 8938 | Trust interests and foreign gifts reported on Form 3520 or 3520-A, and items reported on Forms 5471, 8621 or 8865, need not be reported a second time on Form 8938. The filer reports the number of those forms filed in Part IV of Form 8938, and the asset's value still counts toward the threshold. |
| Owner | Treated as owner of any part of a foreign trust under the grantor trust rules | Form 8938 | Specified foreign financial assets held by the owned portion of a foreign trust (sections 671 through 679) are excluded when the owner timely files Form 3520 for the same tax year, ensures the trust timely files Form 3520-A or a substitute, and reports both filings on Form 8938. |
| FBAR and a trust beneficiary | Trust beneficiary with a financial interest in the trust's foreign financial accounts | FinCEN Form 114 | FinCEN's instructions provide an exception for a trust beneficiary with the financial interest described in section (2)(e) of the definition: the trust, trustee or agent is a U.S. person and files an FBAR disclosing the trust's foreign accounts. |
Notes: Thresholds and exceptions are set out in each form’s instructions, which control. This is informational only, not tax advice.
Sources: IRS statistics of income note on Forms 3520 and 3520-A · IRS reminder to U.S. owners of a foreign trust · IRS Instructions for Form 3520 (distributions) · IRS Instructions for Form 8938 · IRS FATCA information for individuals and summary of FATCA reporting · FinCEN FBAR line item instructions (beneficiary exception) · Day Pitney summary of FBAR reporting · Cassra Minai commentary on Forms 3520 and 8938 · OffshoreTrusts.com.