
How Long Foreign Trusts Can Last
Jersey, BVI, Cayman and Nevis each set their own trust duration rules.
Jersey duration rules
Under Article 15(1) of the Trusts (Jersey) Law 1984, a trust may continue for an unlimited period unless its terms provide otherwise, and no rule against perpetuities or excessive accumulations applies. That is the current rule. Before the Trusts (Amendment No. 4) (Jersey) Law 2006 substituted Article 15, a Jersey trust other than a charitable trust ended no later than its 100th anniversary.[1][2]
The older 100-year rule is history for new analysis, but it can matter for an existing instrument: a trust whose own terms fix a 100-year period still ends when those terms say, although the trustees may be able to appoint the fund into a new trust of unlimited duration if the terms permit. Charitable-purpose trusts were outside the old limit.[2][3]
Terms matter under the unlimited-period version: its default applies only when the trust terms do not provide otherwise. Under this rule, the perpetuity rule and excessive-accumulations rule do not apply to the trust or listed dealings with its assets.[3]
The terms of the instrument remain the controlling check, and Article 15 has changed over time.[2][6]
BVI purpose trusts
BVI purpose trusts are exempt from perpetuity rules, including the rule against perpetual trusts. The exemption covers purpose trusts only, not every type of BVI trust.[4]
A purpose trust instrument may set a date or event for the trust to cease being a purpose trust and provide for disposition of trust assets then. Exemption from perpetuity rules does not itself require an unlimited term.[4]
Cayman Islands duration
An ordinary Cayman Islands trust is subject to a maximum perpetuity period of 150 years under the Perpetuities Act. A STAR trust, whether for purposes, persons, or both, can be perpetual.[5]
Nevis international trusts
Nevis law provides that the rule against perpetuities does not apply to an international trust. Unless its terms provide otherwise, the trust has unlimited duration.[7]
The terms can therefore provide a different duration from the statutory default.[7]
Duration at a glance
| Jurisdiction or trust type | Duration stated | Role of the terms or exception |
|---|---|---|
| Jersey, current Art. 15(1) | Unlimited period | Applies unless terms provide otherwise[1] |
| Jersey, superseded Art. 15 (before 2006) | Until the 100th anniversary, unless terminated sooner | Replaced by the unlimited-period rule; charitable-purpose trusts were outside the old limit[2] |
| BVI purpose trust | Exempt from perpetuity rules | Instrument may specify an ending date or event[4] |
| Cayman Islands trust | 150-year maximum perpetuity period; STAR trusts may be perpetual | May have a specified term[5] |
| Nevis international trust | Unlimited duration by default | Terms may provide otherwise[7] |
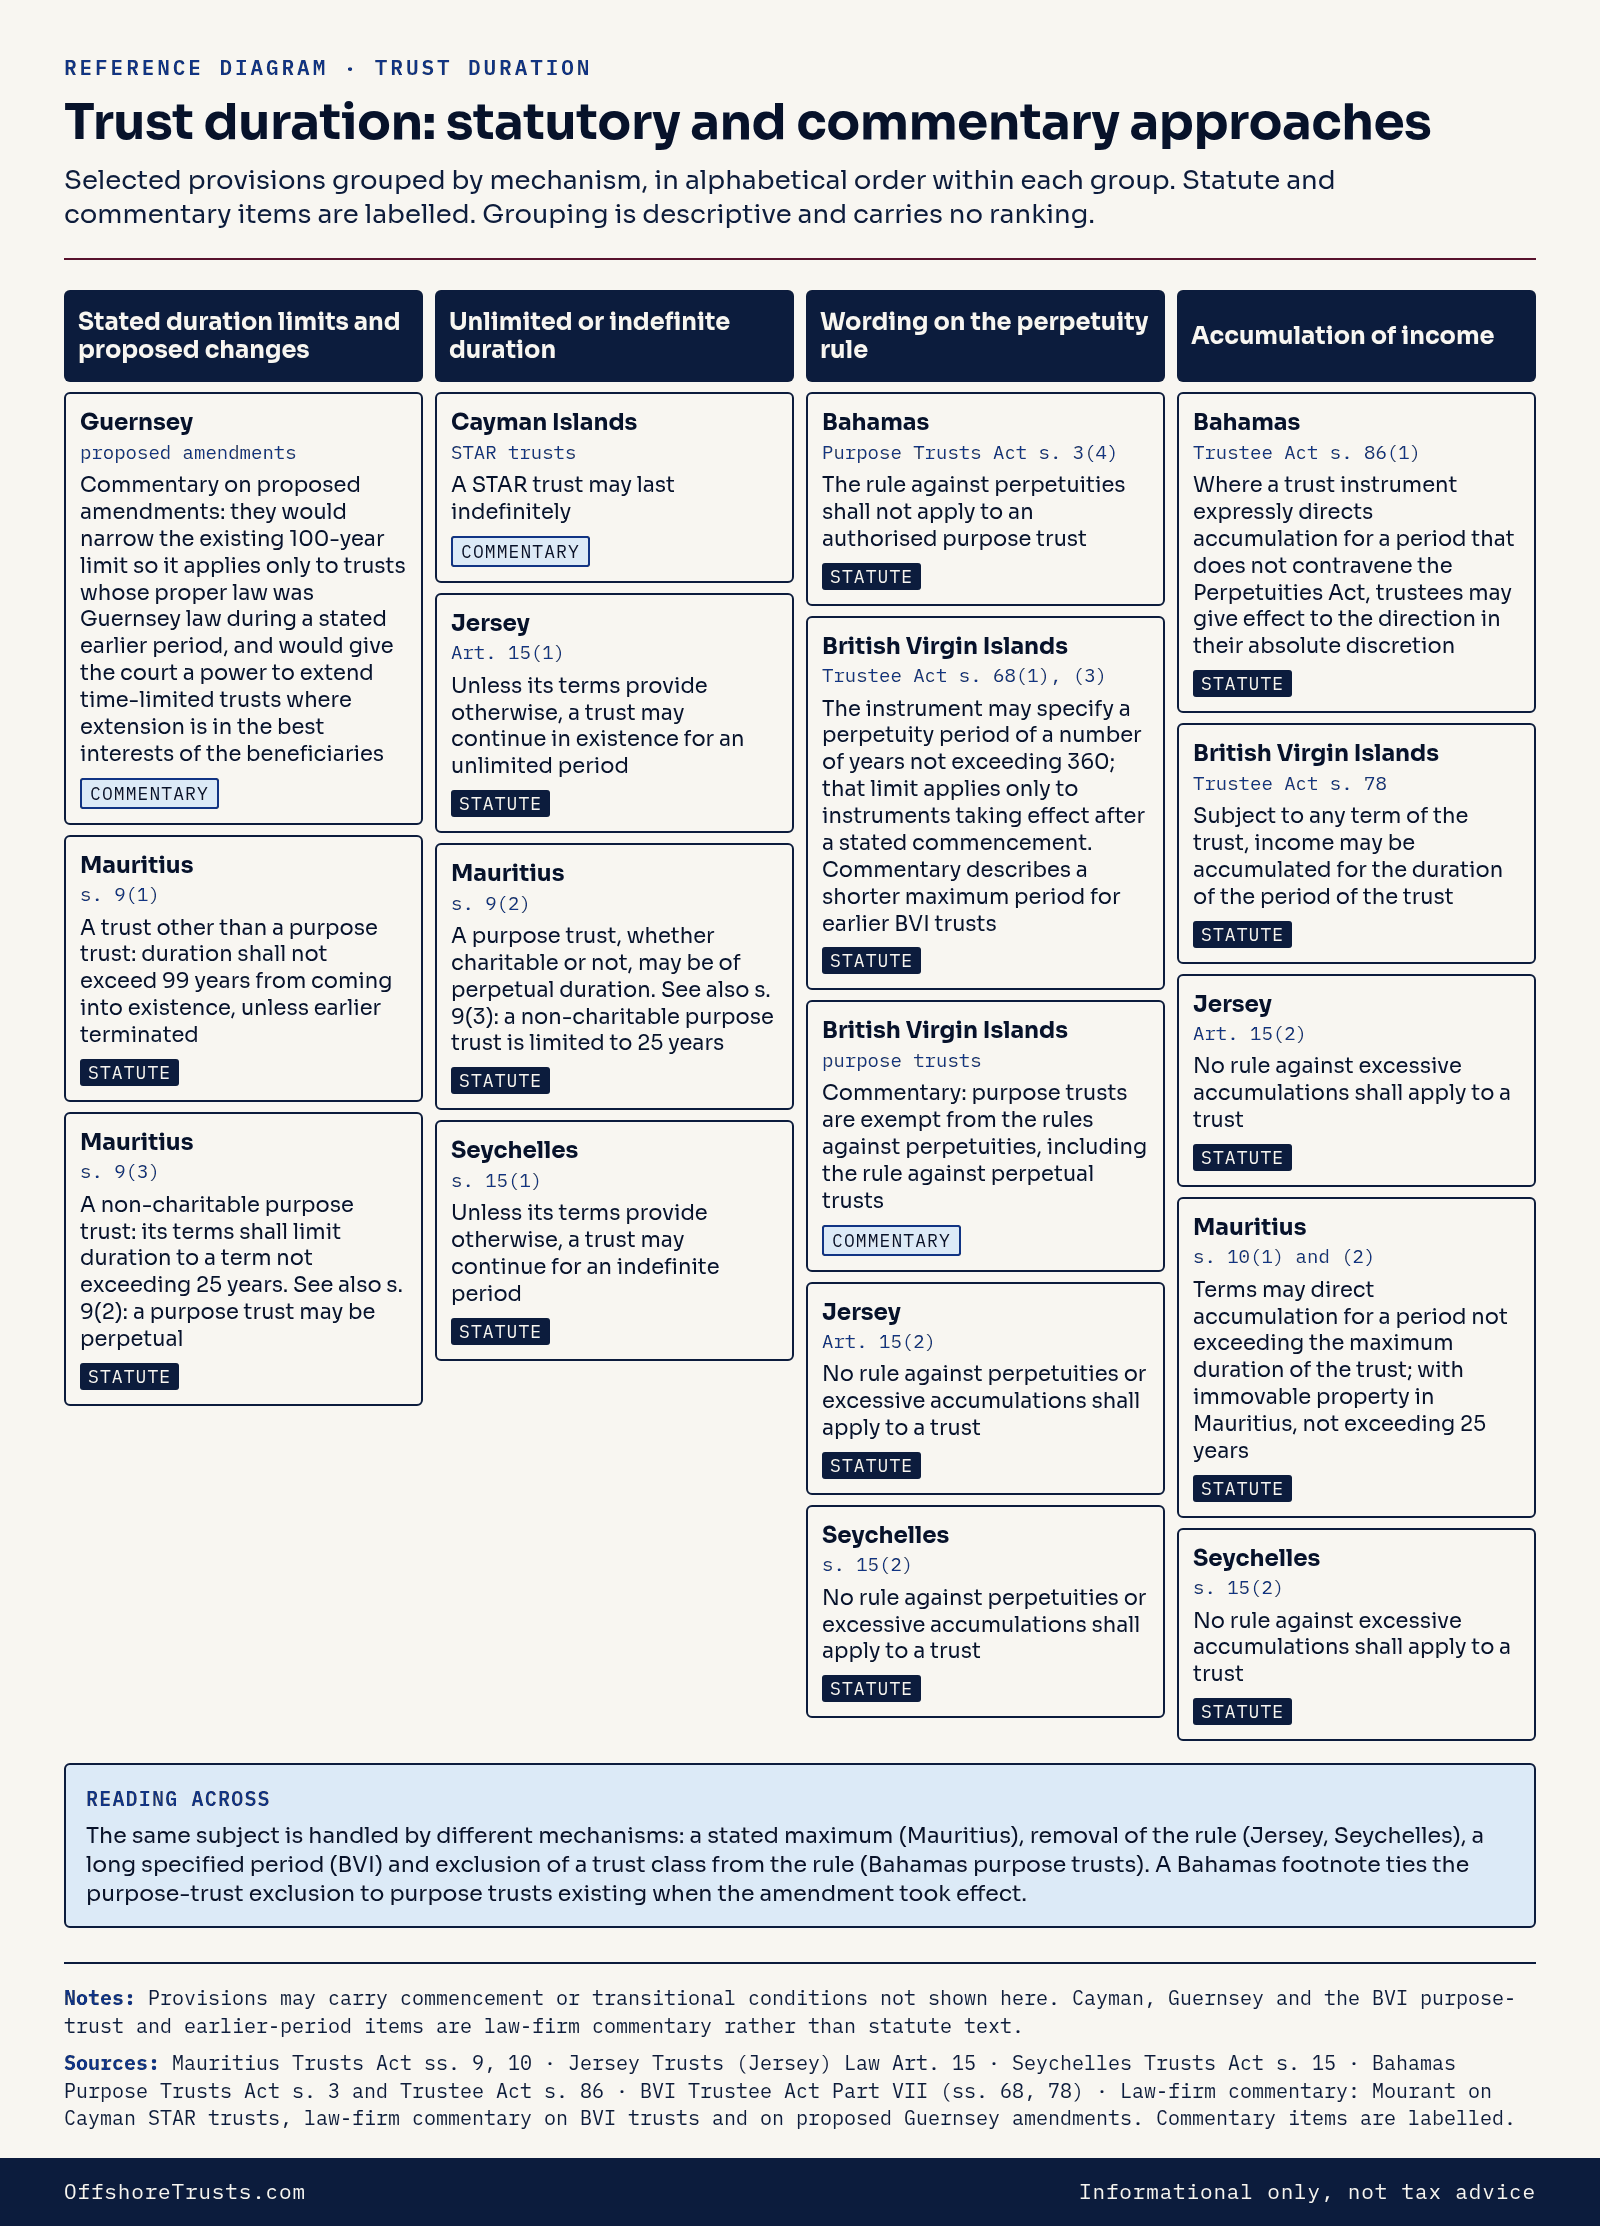
Data table for this infographic
| Mechanism | Jurisdiction | Provision or form | Description | Source type |
|---|---|---|---|---|
| Stated duration limits and proposed changes | Guernsey | proposed amendments | Commentary on proposed amendments: they would narrow the existing 100-year limit so it applies only to trusts whose proper law was Guernsey law during a stated earlier period, and would give the court a power to extend time-limited trusts where extension is in the best interests of the beneficiaries | commentary |
| Stated duration limits and proposed changes | Mauritius | s. 9(1) | A trust other than a purpose trust: duration shall not exceed 99 years from coming into existence, unless earlier terminated | statute |
| Unlimited or indefinite duration | Cayman Islands | STAR trusts | A STAR trust may last indefinitely | commentary |
| Unlimited or indefinite duration | Jersey | Art. 15(1) | Unless its terms provide otherwise, a trust may continue in existence for an unlimited period | statute |
| Unlimited or indefinite duration | Mauritius | s. 9(2) | A purpose trust, whether charitable or not, may be of perpetual duration (as amended in 2011) | statute |
| Unlimited or indefinite duration | Seychelles | s. 15(1) | Unless its terms provide otherwise, a trust may continue for an indefinite period | statute |
| Wording on the perpetuity rule | Bahamas | Purpose Trusts Act s. 3(4) | The rule against perpetuities shall not apply to an authorised purpose trust | statute |
| Wording on the perpetuity rule | British Virgin Islands | Trustee Act s. 68(1), (3) | The instrument may specify a perpetuity period of a number of years not exceeding 360; that limit applies only to instruments taking effect after a stated commencement. Commentary describes a shorter maximum period for earlier BVI trusts | statute |
| Wording on the perpetuity rule | British Virgin Islands | purpose trusts | Commentary: purpose trusts are exempt from the rules against perpetuities, including the rule against perpetual trusts | commentary |
| Wording on the perpetuity rule | Jersey | Art. 15(2) | No rule against perpetuities or excessive accumulations shall apply to a trust | statute |
| Wording on the perpetuity rule | Seychelles | s. 15(2) | No rule against perpetuities or excessive accumulations shall apply to a trust | statute |
| Accumulation of income | Bahamas | Trustee Act s. 86(1) | Where a trust instrument expressly directs accumulation for a period that does not contravene the Perpetuities Act, trustees may give effect to the direction in their absolute discretion | statute |
| Accumulation of income | British Virgin Islands | Trustee Act s. 78 | Subject to any term of the trust, income may be accumulated for the duration of the period of the trust | statute |
| Accumulation of income | Jersey | Art. 15(2) | No rule against excessive accumulations shall apply to a trust | statute |
| Accumulation of income | Mauritius | s. 10(1) and (2) | Terms may direct accumulation for a period not exceeding the maximum duration of the trust; with immovable property in Mauritius, not exceeding 25 years | statute |
| Accumulation of income | Seychelles | s. 15(2) | No rule against excessive accumulations shall apply to a trust | statute |
Reading across: The same subject is handled by different mechanisms: a stated maximum (Mauritius), removal of the rule (Jersey, Seychelles), a long specified period (BVI) and exclusion of a trust class from the rule (Bahamas purpose trusts). In The Bahamas, the purpose-trust exclusion is tied to purpose trusts existing when the amendment took effect.
Notes: Provisions may carry commencement or transitional conditions not shown here. The Cayman STAR trust item, the Guernsey proposed amendments item and the BVI purpose trust item are law-firm commentary and not statute text.
Sources: Mauritius Trusts Act ss. 9, 10 · Jersey Trusts (Jersey) Law Art. 15 · Seychelles Trusts Act s. 15 · Bahamas Purpose Trusts Act s. 3 and Trustee Act s. 86 · BVI Trustee Act Part VII (ss. 68, 78) · Law-firm commentary: Mourant on Cayman STAR trusts, law-firm commentary on BVI trusts and on proposed Guernsey amendments. Commentary items are labelled.
Attribution: OffshoreTrusts.com
Questions and answers
Can a Jersey trust last indefinitely?
Yes. Under Article 15(1) of the Trusts (Jersey) Law 1984 it may continue for an unlimited period unless its terms provide otherwise, and no rule against perpetuities or excessive accumulations applies. An older 100-year limit was replaced in 2006.[1][2]
What happened to Jersey's 100-year limit?
The superseded text of Article 15 ended a Jersey trust, other than a charitable trust, at its 100th anniversary. The Trusts (Amendment No. 4) (Jersey) Law 2006 replaced that limit with the unlimited-period default. A trust whose own terms fix 100 years still ends then.[2]
Can a BVI purpose trust specify when it ends?
Yes. For a purpose trust, its instrument may specify a date or event for the trust to cease being a purpose trust and state how assets will be disposed of then.[4]
Can a Cayman Islands trust have unlimited duration?
Only a STAR trust can be perpetual, whether for purposes, persons, or both.
What is the duration default for a Nevis international trust?
For an international trust, the rule against perpetuities does not apply. Unless the trust terms provide otherwise, an international trust has unlimited duration.[7]
Related resources
Related glossary terms
- Corporate trustee: A corporate trustee is a company that acts as trustee of a trust. Jersey law sets out how a corporate trustee acts and how it relates to individual trustees and trust corporations.
- Enforcer: An enforcer is a person given a role in relation to certain trusts. Jersey and Cayman law describe how enforcers are appointed, with their duties and rights.
- Trust variation: Trust variation means a change to a trust's terms or powers. Jersey, Cayman Islands and Bermuda laws and the Hague Convention address related terms and rules.
Related pages
- Topic guides
- Grantor and nongrantor trust taxation
- The court and control tests for foreign trusts
- How the IRS classifies trusts for U.S. tax purposes
- Protector powers, consent and duties
- Dynasty trusts and the generation-skipping transfer tax: How dynasty trusts meet the generation-skipping transfer tax: GST events, exemption allocation, inclusion ratios and federal transfer tax reporting rules.
Sources and data notes
- admin.jerseylaw.je, Trusts (Jersey) Law 1984. https://admin.jerseylaw.je/laws/current/l_11_1984. Retrieved .
- jerseylaw.je, Trusts (Jersey) Law 1984. https://jerseylaw.je/laws/superseded/Pages/2004/13.875.aspx. Retrieved .
- jerseylaw.je, Trusts (Jersey) Law 1984. https://www.jerseylaw.je/laws/current/l_11_1984_20260319. Retrieved .
- harneys.com, BVI trusts: purpose trusts. https://www.harneys.com/insights/bvi-trusts-purpose-trusts/. Retrieved .
- mourant.com, Cayman Islands: Trusts, Mourant. https://www.mourant.com/guides/cayman-islands-trusts/. Retrieved .
- mourant.com, Jersey: Trusts, Mourant. https://www.mourant.com/guides/jersey-trusts/. Retrieved .
- nevisfsrc.com, Nevis International Exempt Trust Ordinance, Cap. 7.03 (N). https://www.nevisfsrc.com/wp-content/uploads/2023/06/Ch-07.03N-Nevis-International-Exempt-Trust-Ord.pdf. Retrieved .
Dates in this block record when each source was read for this page.