
Trust duration
The Hague Convention describes trust duration as a matter governed by the law applicable to a trust. Trust duration relates to trust terms, governing law, and termination.
Meaning and governing law
The Hague Convention describes trust duration as the period a trust may continue, with applicable law governing restrictions on that duration. Its Article 8 places duration restrictions alongside rules on accumulating trust income, variation or termination, and distribution of trust assets.[1]
Article 8 says that the law chosen under Article 6, or identified under Article 7, governs a trust's validity and construction, as well as its effects and administration. A severable aspect, particularly administration, may instead be governed by a different law under Article 9. The Convention therefore links duration to the governing law and its treatment of the trust's terms.[1]
The Convention defines a trust as a legal relationship created during life or at death when a settlor places assets under a trustee's control for a beneficiary or specified purpose. Its characteristics include a separate fund, title held by the trustee or another person for the trustee, and trustee powers and duties tied to the trust terms and law.[1]
A domestic statutory example
Jersey's Trusts Law sets a default duration rule: unless the trust terms provide otherwise, a trust may continue without a specified end period. The section also says that perpetuities and excessive accumulations rules do not apply to a trust or to specified transfers and applications of trust assets.[3]
The same Jersey section addresses assets moved from one trust to another. Unless the first trust's terms say otherwise, an advancement, appointment, payment, or application to another trust remains valid even if the receiving trust may continue past the date when the first trust has to terminate. Duration thus can differ between connected trusts.[3]
Bermuda's statute defines a purpose trust as a trust created for one or more non-charitable purposes, subject to conditions. Those purposes must be sufficiently certain for the trust to be carried out, must be lawful, and must be consistent with public policy, and the trust must be created in writing.[5]
For that statutory category, Bermuda disapplies the rule that limits how long trust capital may remain unexpendable to the perpetuity period.[5]
Duration relates to perpetuity rules, accumulation of income, the trust terms, and termination. The Hague Convention treats these as matters of applicable law, while the Jersey and Bermuda statutes supply particular rules for the trusts they cover.[1][3]
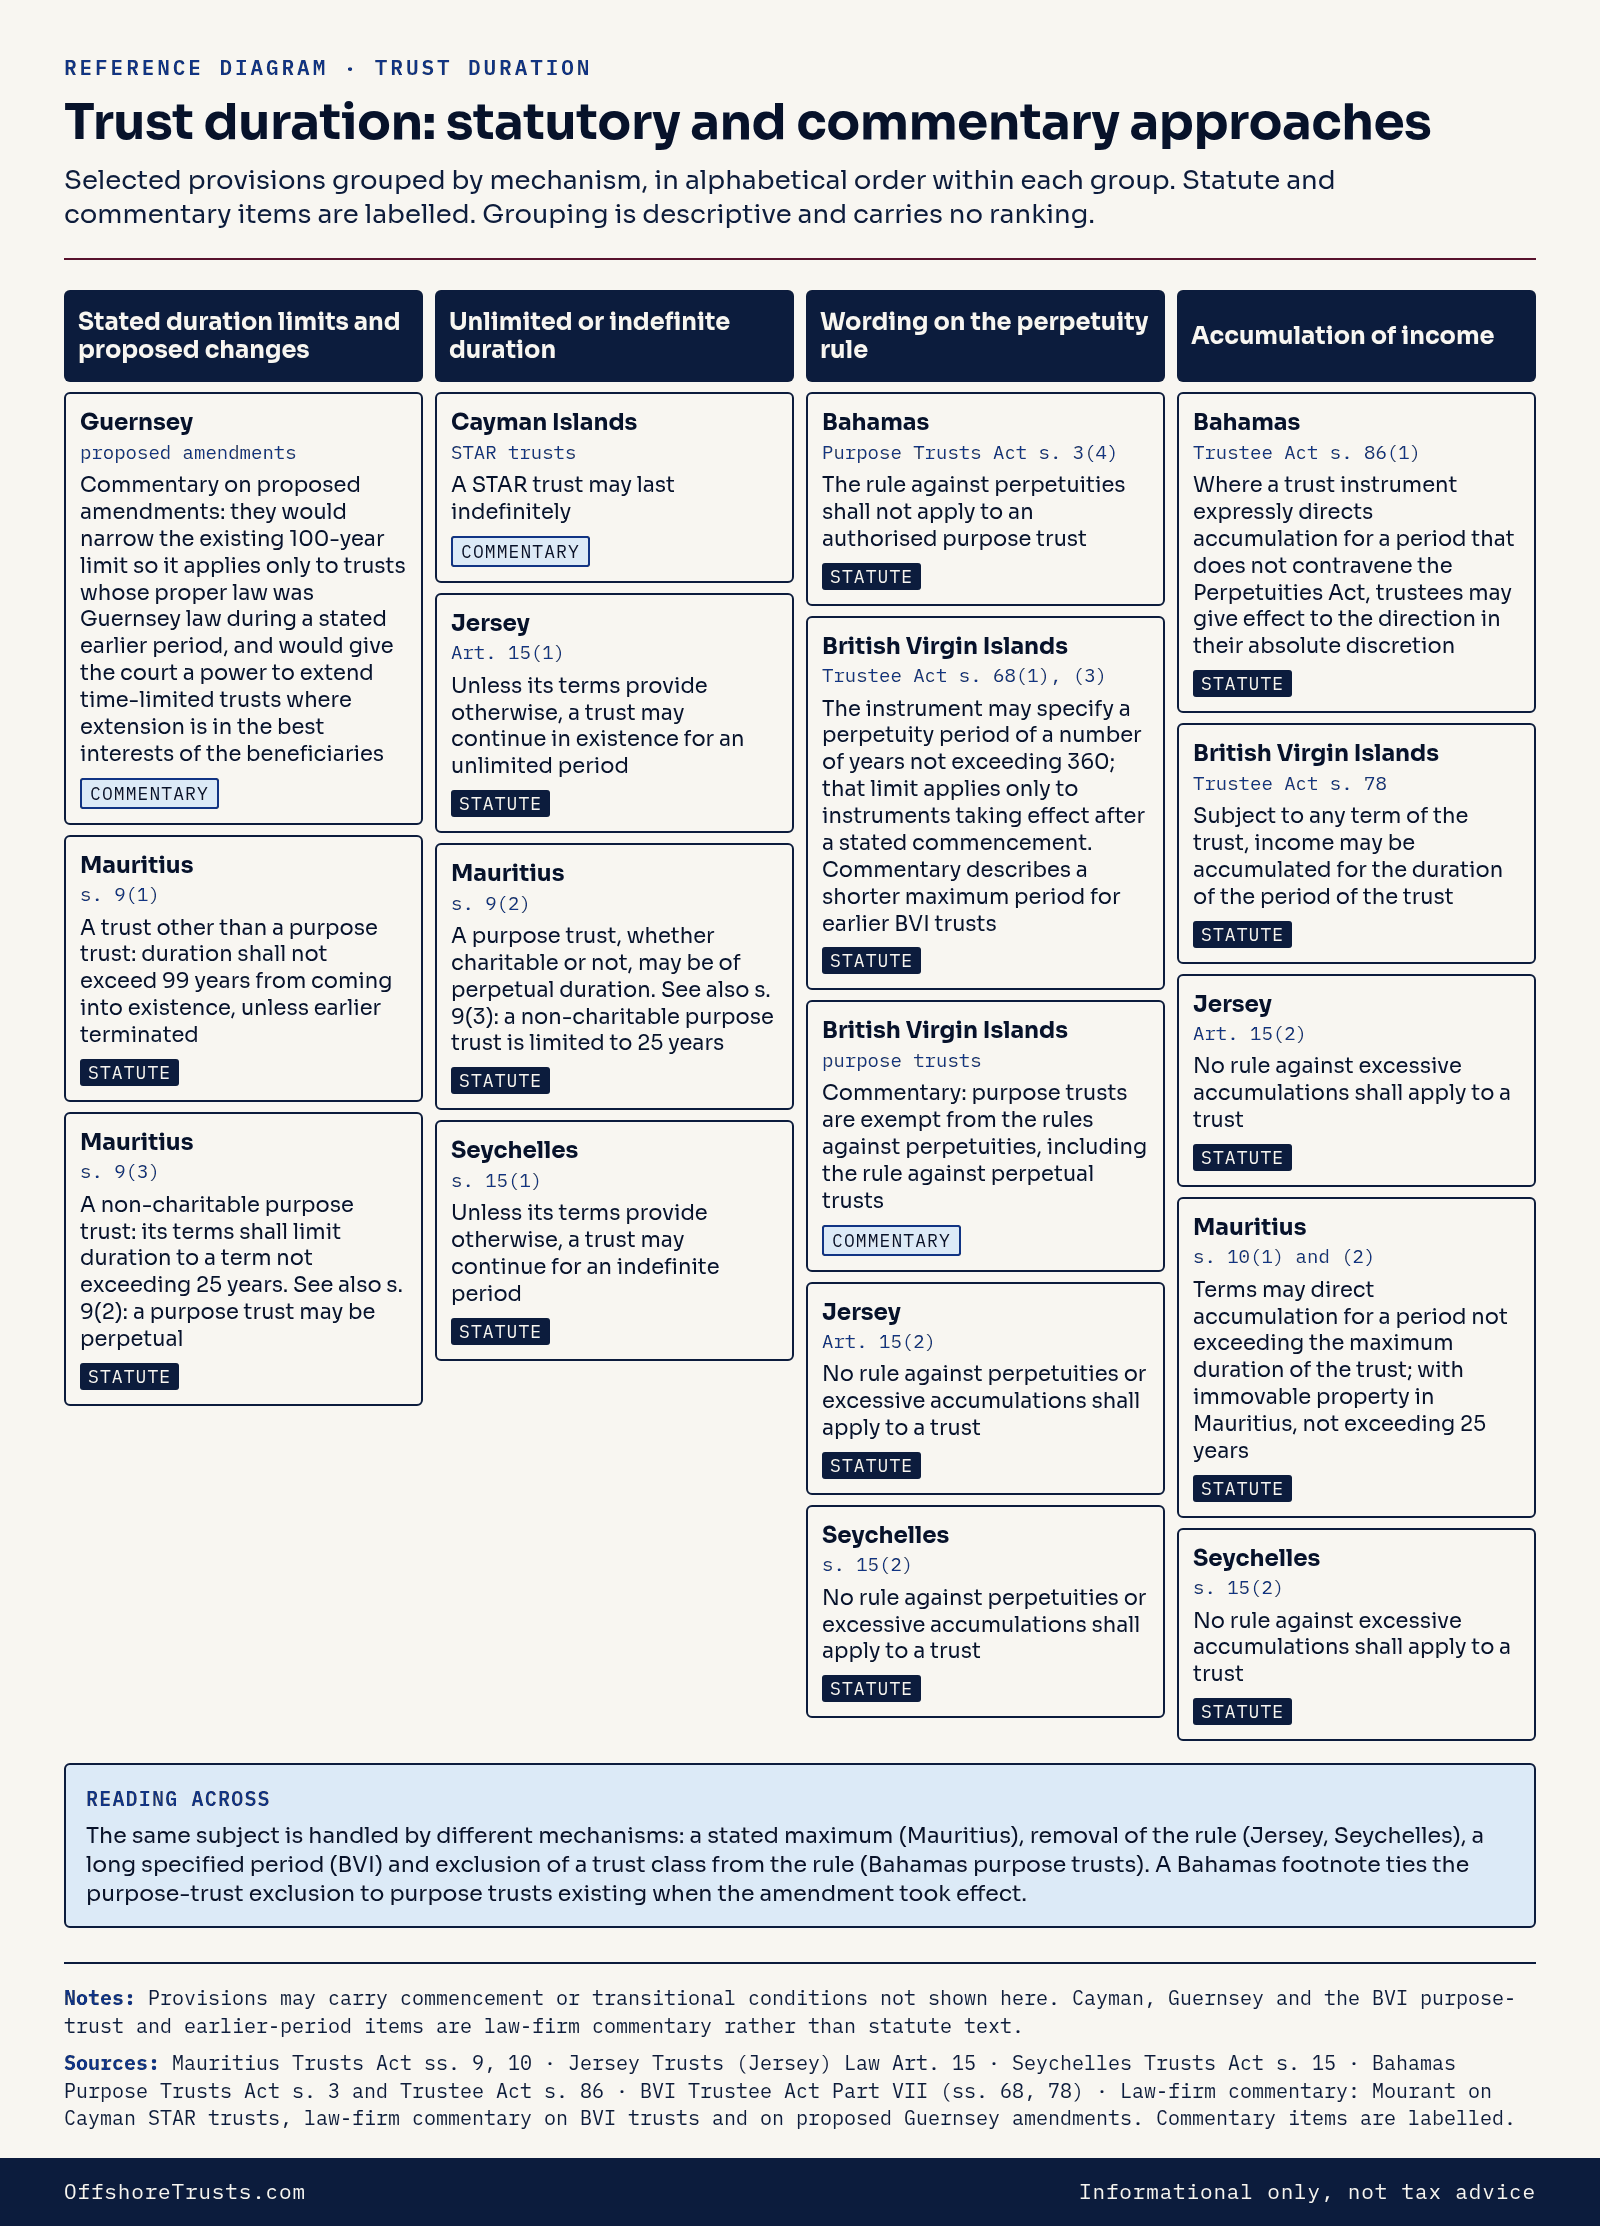
Data table for this infographic
| Mechanism | Jurisdiction | Provision or form | Description | Source type |
|---|---|---|---|---|
| Stated duration limits and proposed changes | Guernsey | proposed amendments | Commentary on proposed amendments: they would narrow the existing 100-year limit so it applies only to trusts whose proper law was Guernsey law during a stated earlier period, and would give the court a power to extend time-limited trusts where extension is in the best interests of the beneficiaries | commentary |
| Stated duration limits and proposed changes | Mauritius | s. 9(1) | A trust other than a purpose trust: duration shall not exceed 99 years from coming into existence, unless earlier terminated | statute |
| Unlimited or indefinite duration | Cayman Islands | STAR trusts | A STAR trust may last indefinitely | commentary |
| Unlimited or indefinite duration | Jersey | Art. 15(1) | Unless its terms provide otherwise, a trust may continue in existence for an unlimited period | statute |
| Unlimited or indefinite duration | Mauritius | s. 9(2) | A purpose trust, whether charitable or not, may be of perpetual duration (as amended in 2011) | statute |
| Unlimited or indefinite duration | Seychelles | s. 15(1) | Unless its terms provide otherwise, a trust may continue for an indefinite period | statute |
| Wording on the perpetuity rule | Bahamas | Purpose Trusts Act s. 3(4) | The rule against perpetuities shall not apply to an authorised purpose trust | statute |
| Wording on the perpetuity rule | British Virgin Islands | Trustee Act s. 68(1), (3) | The instrument may specify a perpetuity period of a number of years not exceeding 360; that limit applies only to instruments taking effect after a stated commencement. Commentary describes a shorter maximum period for earlier BVI trusts | statute |
| Wording on the perpetuity rule | British Virgin Islands | purpose trusts | Commentary: purpose trusts are exempt from the rules against perpetuities, including the rule against perpetual trusts | commentary |
| Wording on the perpetuity rule | Jersey | Art. 15(2) | No rule against perpetuities or excessive accumulations shall apply to a trust | statute |
| Wording on the perpetuity rule | Seychelles | s. 15(2) | No rule against perpetuities or excessive accumulations shall apply to a trust | statute |
| Accumulation of income | Bahamas | Trustee Act s. 86(1) | Where a trust instrument expressly directs accumulation for a period that does not contravene the Perpetuities Act, trustees may give effect to the direction in their absolute discretion | statute |
| Accumulation of income | British Virgin Islands | Trustee Act s. 78 | Subject to any term of the trust, income may be accumulated for the duration of the period of the trust | statute |
| Accumulation of income | Jersey | Art. 15(2) | No rule against excessive accumulations shall apply to a trust | statute |
| Accumulation of income | Mauritius | s. 10(1) and (2) | Terms may direct accumulation for a period not exceeding the maximum duration of the trust; with immovable property in Mauritius, not exceeding 25 years | statute |
| Accumulation of income | Seychelles | s. 15(2) | No rule against excessive accumulations shall apply to a trust | statute |
Reading across: The same subject is handled by different mechanisms: a stated maximum (Mauritius), removal of the rule (Jersey, Seychelles), a long specified period (BVI) and exclusion of a trust class from the rule (Bahamas purpose trusts). In The Bahamas, the purpose-trust exclusion is tied to purpose trusts existing when the amendment took effect.
Notes: Provisions may carry commencement or transitional conditions not shown here. The Cayman STAR trust item, the Guernsey proposed amendments item and the BVI purpose trust item are law-firm commentary and not statute text.
Sources: Mauritius Trusts Act ss. 9, 10 · Jersey Trusts (Jersey) Law Art. 15 · Seychelles Trusts Act s. 15 · Bahamas Purpose Trusts Act s. 3 and Trustee Act s. 86 · BVI Trustee Act Part VII (ss. 68, 78) · Law-firm commentary: Mourant on Cayman STAR trusts, law-firm commentary on BVI trusts and on proposed Guernsey amendments. Commentary items are labelled.
Attribution: OffshoreTrusts.com
Questions and answers
What determines restrictions on a trust's duration under the Hague Convention?
The Convention assigns restrictions on duration to the law governing the trust. Article 8 places that issue among matters governed by the law identified under Articles 6 or 7.[1]
Does the Jersey statute set a default duration?
Yes. Unless its terms provide otherwise, a Jersey trust may continue for an unlimited period. The statute also addresses perpetuities and excessive accumulations.[3]
How does the Jersey statute treat a transfer to another trust?
Unless the first trust's terms provide otherwise, a transfer of assets to another trust may be valid even when that trust can continue beyond the first trust's required termination date.[3]
What does the Bermuda statute say about duration for purpose trusts?
For a purpose trust, the statute says the rule limiting how long capital may remain unexpendable to the perpetuity period does not apply. It defines this category by non-charitable purposes and specified conditions.[5]
Related terms
- Trust: The Hague Convention describes a trust as a relationship in which a settlor places assets under a trustee's control for beneficiaries or a specified purpose.
- Proper law of a trust: The Jersey Trusts Law defines proper law as the jurisdiction's law expressed or implied in trust terms, or most closely connected to the trust when created.
- Purpose trust: A purpose trust holds property for purposes, not for beneficiaries, and relies on an enforcer. Bermuda and Jersey define it differently, as does Cayman.
Related guides and articles
- How Long Foreign Trusts Can Last: How long a trust can last in Jersey, BVI, Cayman and Nevis, including Jersey's unlimited-period default since 2006 and the 100-year limit it replaced.
- The Hague Trusts Convention explained: The Hague Trusts Convention addresses which law governs a trust and how a trust is recognized, while preserving each state's fiscal powers over trusts and tax.
- What a trust means under U.S. and international law: Trust terms and structure, the Hague Convention's rules, and U.S. tax classification and limited reporting rules, all explained plainly for U.S. citizens.
Related pages
Sources and data notes
- HCCH, 1985 Hague Trusts Convention. https://www.hcch.net/en/instruments/conventions/full-text/?cid=59. Retrieved .
- Internal Revenue Service, 26 CFR 301.7701-4. https://www.ecfr.gov/current/title-26/section-301.7701-4. Retrieved .
- Jersey Legal Information Board, Trusts (Jersey) Law 1984. https://jerseylaw.je/laws/current/l_11_1984. Retrieved .
- Cayman Islands Legislature, Trusts Act (2021 Revision). https://legislation.gov.ky/cms/images/LEGISLATION/PRINCIPAL/1967/1967-0006/1967-0006_2021%20Revision.pdf. Retrieved .
- Legislature of Bermuda, Trusts (Special Provisions) Act 1989. https://bermuda.fm/legislation/1591. Retrieved .
Dates in this block record when each source was read for this page.